October 26, 2026
The Week Ahead
Cotton heads into a busy week with plenty happening outside the cotton market that could influence prices. Wednesday’s Fed decision, rising crude oil prices, and continued selling across agriculture will be worth watching as the market works through seasonal harvest pressure.
- Wednesday’s Fed decision will be the biggest event on the economic calendar. Another rate hike this week looks unlikely, but hotter inflation readings and Brent crude oil prices climbing above $117 per barrel have raised expectations for another hike before year-end.
- The Fed’s comments will be just as important as the decision itself, particularly for the direction of the dollar and commodity markets. Thursday’s GDP and PCE inflation reports will also be worth watching, along with several other central bank decisions throughout the week.
- Agricultural markets are heading into a seasonally weaker stretch, but some of the recent selling pressure may be easing. Funds have spent seven consecutive weeks reducing their bets on higher prices, reversing much of the buying seen in August. While there’s still room for additional selling, a good portion of that pressure may already be behind us. Late October and early November aren’t typically the strongest periods for cotton, but with so much selling already taking place, it will be interesting to see whether prices can find some stability.
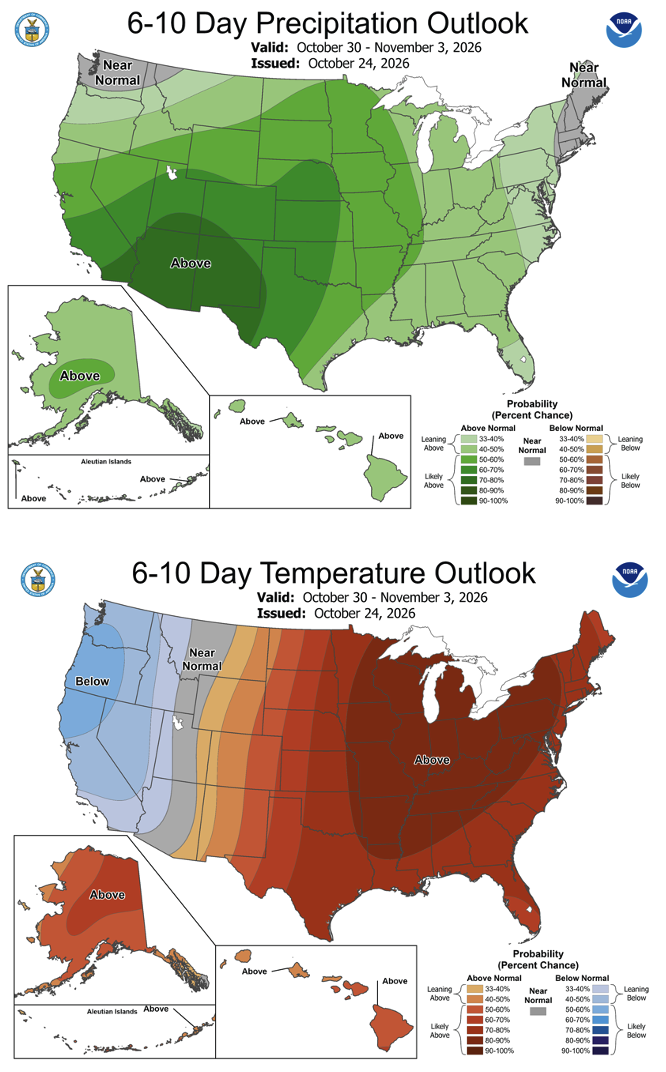
- Harvest progress and demand will help determine whether cotton can find some support of its own. More of the U.S. crop is making its way to market, and favorable harvest weather has helped keep things moving, although rainy weather is in the forecast for the week. Lower prices have encouraged some buying interest, but stronger, more consistent demand is still needed. Monday’s crop progress report and Thursday’s export sales report will provide another look at how both sides are shaping up.
 Market Recap
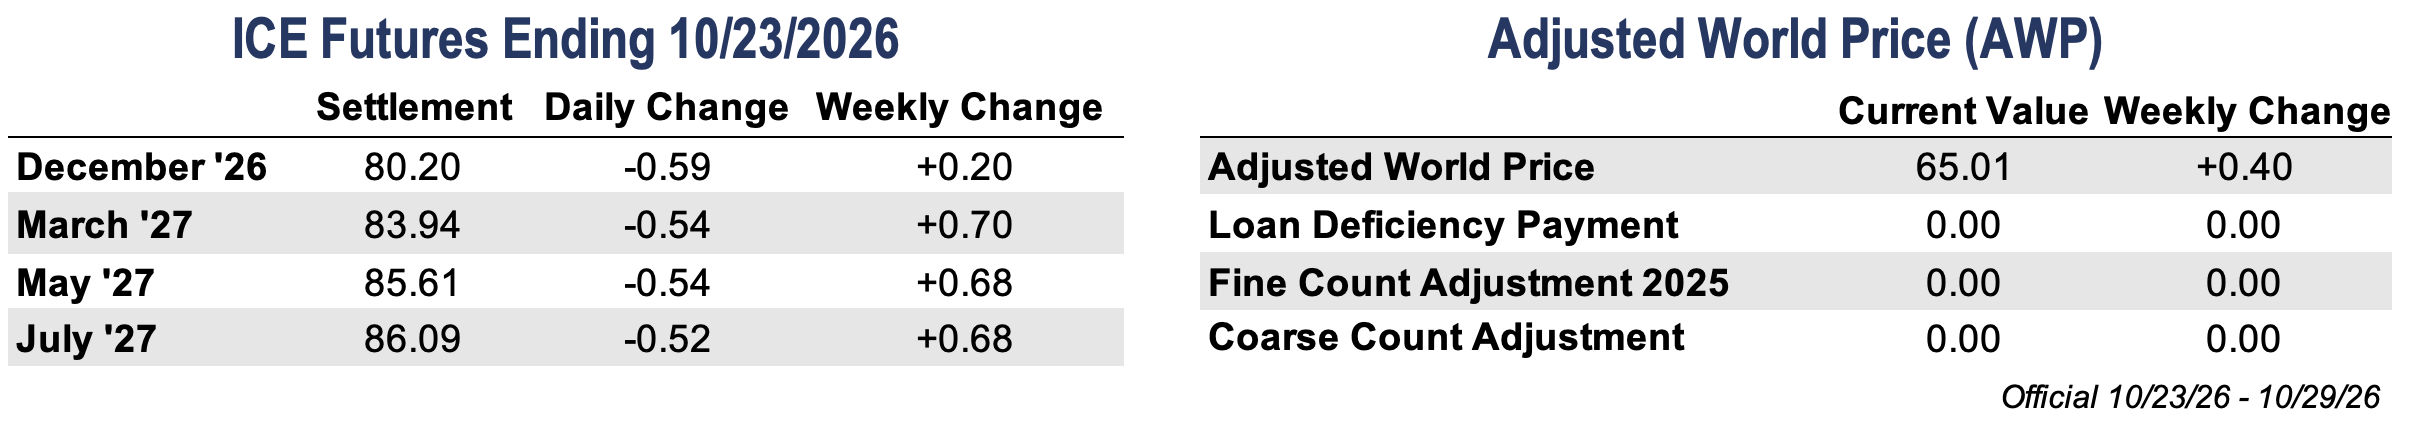
- Cotton managed a small gain last week, but December futures are having a hard time getting much beyond 80 cents. December gained 20 points to settle at 80.20 cents per pound, trading between 79.86 and 82.10 throughout the week. Wednesday brought some encouragement as prices briefly pushed above the 100-day moving average, but those gains didn’t hold. The market has found some buying interest at these lower levels, although even improving export demand hasn’t been enough to generate much upward momentum.
- Much of the action last week happened outside of outright futures prices. Cotton open interest topped 400,000 contracts for the first time, while the December/March spread widened to 3.74 cents, its widest level for this point in the season since 2008. Traders are increasingly focused on moving out of December and into later contracts, with the growing difference between the two adding pressure.
- On a more encouraging note, managed money was a small net buyer of cotton last week, a change from the selling we’ve seen recently. Still, the lack of interest in betting on a December rally suggests traders aren’t expecting much upside before the contract expires.
- Harvest made a big jump last week, but the focus is increasingly shifting toward the quality of the crop coming out of the field. The U.S. crop was 41% harvested at the start of last week, up from 31% the previous week and ahead of the five-year average of 37%. Recent freezes and additional rainfall across parts of West Texas have raised more concerns about quality, particularly with so much cotton still open in the fields. More rain is in the forecast, which isn’t particularly welcome at this stage of harvest. As classing picks up, we’ll get a better idea of how much of the crop has been affected and what that could mean for available supplies.
Economic and Policy Outlook
- Crude oil prices climbed sharply late last week as escalating tensions in the Middle East raised concerns about potential supply disruptions. Both WTI and Brent crude posted weekly gains, adding to inflation concerns following the hotter readings earlier this month. Higher energy costs are particularly unwelcome for growers in the middle of harvest, especially as the administration looks for ways to provide some fuel relief.
- Brazil’s presidential election brought a surprise over the weekend, with President Lula winning reelection over Flávio Bolsonaro. The Brazilian real had strengthened roughly 4.5% over the past three weeks as markets anticipated a Bolsonaro victory, but the unexpected result sent the currency sharply lower in overnight trading. A weaker real makes Brazilian cotton more competitive in the export market and could encourage additional farmer selling, adding another potential headwind for U.S. cotton prices. With Brazil already actively competing for export business, currency movements are worth watching in the coming weeks.
- USDA announced two new initiatives last week aimed at easing financial pressure on agricultural producers. The $8 billion Harvest Fuel Relief program will provide one-time payments to help offset higher fuel and input costs during the 2026 crop year. Payments will be based on planted acreage, production costs, and projected yields and prices, with commodity-specific rates expected in November. USDA also announced more than $1.3 billion in proposed investments across eight domestic fertilizer manufacturing projects, including approximately $573 million in federal funding. The goal is to expand domestic fertilizer supplies and improve affordability, although those benefits will take longer to reach growers.
Supply and Demand Overview
- Upland sales picked up this week, totaling 199,600 bales. Vietnam led purchases by a wide margin, followed by Bangladesh and Turkey. Sales were above the recent average, providing another encouraging sign that buyers are finding some value at these lower prices. China was notably absent from the buying, with a small cancellation for the week.
- Shipments also showed some welcome improvement, reaching 196,400 bales. Vietnam was the top destination, followed by Pakistan and Turkey. Shipments were well above the recent average, which is encouraging after several slower weeks. There is still some ground to make up to reach USDA’s export projection, but this was a step in the right direction.
- Pima had a quieter week, with sales totaling 1,900 bales and shipments reaching 7,500 bales. Vietnam led new purchases, while India accounted for the bulk of exports.
- Overall, this past week was a better week for U.S. cotton demand, particularly on the shipment side. Sales have shown some improvement recently, and it’s encouraging to see more cotton actually moving. China is still a missing piece of the puzzle, but buying interest from other markets has helped fill some of that gap. The bigger question is whether this pace can be sustained as the U.S. works through its crop and competes with continued Brazilian supplies.
The Seam®
- As of Friday afternoon, grower offers totaled 10,344 bales. The past week, 6,458 bales traded on the G2B platform received an average price of 74.44 cents per pound. The average loan redemption rate (LRR) was 56.34, bringing the average premium over the LRR to 18.10 cents per pound.
- Note: The Loan Redemption Rate (LRR) is the loan rate minus the current Loan Deficiency Payment (LDP).